Scaffolders’ liability insurance
Scaffolding Insurance
for Professionals
As a scaffolder, insurers see you as one of the highest risk trades in the UK construction industry.
That’s why it can be so hard to buy Public Liability insurance for scaffolding contracts: plenty of companies won’t even give you a quote, and those that do insist on strict health and safety regulations.


You can’t skimp, though. In these litigious times it’s not an option. Whatever work you’re doing, and no matter how long you’ve been in the scaffolding business, you need sufficient liability cover to suit both your budget and the types of scaffolding jobs you carry out.
Insurers also want to know exactly what you build. The type of structure changes the risk, and the public liability exposure that comes with it, so our guides cover each of the seven main scaffold types:
Your cover
What should your scaffold insurance cover you for?
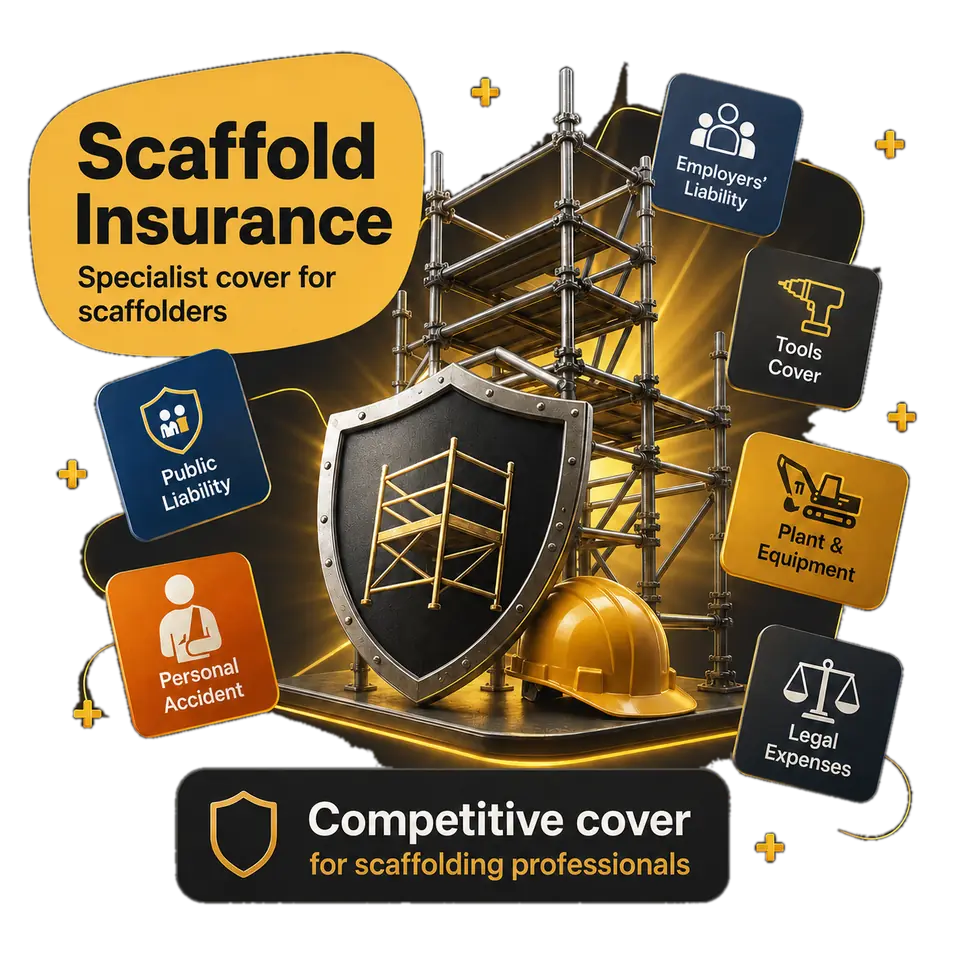
A basic policy needs to cover you for:
- Public Liability insurance to cover the public against negligence
- Corporate manslaughter to cover you if the worst happens
- Employers’ liability if you employ anyone, including labour-only subcontractors
- Legal cover for costs under the Health and Safety at Work Act
For extra protection, you can also choose:
- Personal accident insurance for you and your employees
- Equipment damage cover for fire, theft and other perils
- Plant and tools cover to protect the equipment you rely on
- Hired-in property cover for any equipment you rent
- Terrorism cover for the unexpected
Insurance guides
Scaffolding insurance explained
Policies for scaffolders are built from a handful of standard covers. These guides explain each one in plain English: what it pays for, what it excludes, and the questions a broker will ask.
Public liability insurance
The core cover. Limits, height and depth conditions, exclusions, and what a claim actually looks like.
Employers’ liability insurance
A legal requirement once you employ anyone, including labour-only subcontractors on your gang.
How much does it cost?
What drives a scaffolder’s premium, typical price ranges, and how to bring the number down.
Sole traders & labour-only
Cover for one-man bands and operatives working on other people’s scaffolds.
Plant, tools & contractors all risks
Protecting tubes, boards, fittings, vehicles and hired-in kit against theft and damage.
Roofing insurance
Roofers face the same height risk plus heat. What their liability policies look like.
Getting the right quote
What to look for in scaffold insurance
To get the best price and the right liability cover, you need to be very clear about the insurance you need:
- Are you a contractor, labour-only subcontractor or sole trader, or a bona fide subcontractor?
- How much scaffolding experience do you have?
- What height are you working at?
Our guide to what scaffolding insurance costs explains how each of those answers moves the premium. No two policies will be the same: cover changes from business to business, so it’s worth getting a personalised quote from a specialised broker who fully understands the precise level of Liability Insurance scaffolders need for both themselves, and the general public.
It’s your responsibility to ensure that you carry the appropriate level of Liability Insurance on every scaffolding contract you or your company is engaged in.
Get a scaffolding insurance quote
Tell us about your contracts and we’ll point you towards the right level of cover.